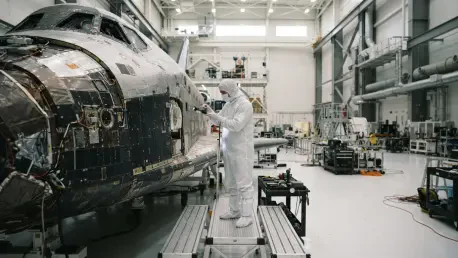
The shift toward private sector dominance in aerospace is blurring the lines between professional astronautics and civilian recreational travel beyond the atmosphere. What was once the exclusive domain of national governments and elite military pilots has evolved into a high-stakes arena for commercial enterprises and luxury adventure seekers. This transition is not merely a matter of scientific curiosity but a profound shift in how the global economy interacts with the cosmos. As rockets become more reliable and launch costs continue to decrease, the aspiration of viewing the Earth against the blackness of space is becoming a tangible reality for a growing segment of the global population. This emerging market is defined by a move toward experiential travel, where the ultimate status symbol is no longer a terrestrial asset but a journey to the final frontier. The integration of advanced engineering with luxury hospitality is creating a new vertical in the travel industry that promises to reshape our understanding of exploration and commerce in the modern age. As more providers enter the fray, the competitive landscape is pushing the boundaries of what is possible, ensuring that space is the next major destination for those seeking the ultimate adventure. This momentum reflects a broader societal shift where exploration is valued as a peak luxury experience, supported by a sophisticated ecosystem of aerospace engineers, luxury travel planners, and private investors who recognize the immense potential of this niche market.
Projecting Financial Growth and Market Expansion
Monitoring Global Market Valuation: A Financial Analysis
Financial indicators suggest that the space tourism sector is successfully navigating its transition from a speculative venture to a stabilized commercial industry. In 2025, the market reached a valuation of approximately $1.48 billion, and as the industry moves through 2026, it is expected to climb to $1.76 billion. This represents a robust compound annual growth rate of 19.1%, a figure that underscores the significant appetite for private extraterrestrial travel. Analysts monitoring these trends suggest that this momentum is unlikely to slow down as more flight providers enter the operational phase of their business models.
By the year 2030, the leisure space tourism industry is projected to more than double its current value, reaching an estimated $3.49 billion. This sustained growth is a testament to the maturation of launch technologies and the establishment of a reliable customer pipeline that views orbital travel as a viable and desirable pursuit. The long-term financial outlook for the industry is bolstered by the shift toward regularized service offerings that provide predictable revenue streams for aerospace companies. This stabilization allows for better capital allocation toward expanding fleet sizes and improving the overall passenger experience across the global market.
Identifying Primary Drivers: Technological and Social Shifts
Several critical factors are accelerating the expansion of the leisure space market, most notably the development of reusable launch systems that significantly lower entry costs. By allowing rockets to be flown multiple times, companies have rewritten the economic playbook for aerospace. This technological leap has made frequent launches a reality, providing the volume necessary to sustain a multi-billion-dollar market. Furthermore, the infusion of private investment from venture capitalists has provided the necessary capital for advanced passenger infrastructure, such as specialized launch facilities and training centers.
Beyond the technical aspects, heightened media coverage and a growing density of high-net-worth individuals have transformed the “once-in-a-lifetime” appeal of orbital views into a consistent demand for premium adventure travel. The cultural visibility of successful civilian missions has demystified the process, making it appear as a safe and aspirational luxury service. As the global elite seek out increasingly unique and exclusive experiences, the allure of seeing the Earth from orbit remains unparalleled. This synergy of technological capability and a growing consumer base ensures that the market for space tourism continues to expand.
Analyzing Investment and Regional Powerhouses
Evaluating Private Capital: Defense and Synergy
A significant trend in industry funding is the synergy between commercial tourism and governmental defense interests. In 2025, security and defense-oriented firms accounted for 30% of investments in certain regions, proving that high-performance vehicle development benefits both military and civilian sectors. This overlap ensures that research and development costs are shared, accelerating the deployment of next-generation engines and thermal protection systems. Such dual-use technology is vital for maintaining a competitive edge in both national security and the high-end commercial travel market.
Investment patterns also show a strong localized interest, with a vast majority of funding rounds being led by regional entities looking to establish dominance in the global space race. For instance, European-based investors are increasingly focusing on domestic ventures to ensure they are not left behind by the rapid progress seen in North America. This localized strategy is crucial for building a resilient supply chain and fostering a workforce capable of sustaining long-term aerospace operations. The concentration of capital within specific regions helps create specialized hubs that drive innovation and regional economic growth.
Mapping Leading Hubs: Regional Market Dynamics
The geographical landscape of space tourism features a distinct division between established leaders and rapidly growing markets. North America currently holds the largest market share due to its advanced aerospace infrastructure and a proactive regulatory environment for human spaceflight. The presence of major industry pioneers and extensive launch facilities in Florida and Texas provides a significant advantage. This established ecosystem allows for a higher frequency of launches and a more mature service model that caters to the largest concentration of potential customers in the world.
However, the Asia-Pacific region is emerging as the fastest-growing market, fueled by rapid economic expansion and government-backed initiatives in countries such as China, India, and Japan. These nations are investing heavily in domestic space programs that are increasingly open to commercial partnerships and tourism initiatives. The rapid growth of the billionaire class in this region also creates a massive untapped market for luxury space travel. As local tech giants continue to diversify into aerospace, the competition between established Western firms and emerging Eastern players is expected to intensify through 2030.
Navigating Future Trends and FAQ
Transitioning to Luxury: Customization and Habitats
As the market matures through 2030, the industry is moving away from a standardized model to favor highly customized, premium packages. While suborbital flights remain common, there is an increasing appetite for longer orbital stays and lunar missions that offer personalized itineraries. These journeys are being designed to include bespoke experiences such as gourmet zero-gravity dining and private observation decks. The shift toward customization ensures that every aspect of the journey meets the exacting standards of the world’s most discerning travelers.
The development of private space habitats is expected to supplement or replace existing stations, providing a more resort-like atmosphere for travelers seeking exclusive zero-gravity experiences. Companies are already working on modular stations that offer expanded living spaces and improved life-support systems specifically for civilian use. These habitats will serve as the premier destinations for orbital tourism, offering a level of comfort and privacy that was previously impossible in government-run research stations. This infrastructure is the key to extending the duration of space stays and increasing the market value.
Frequently Asked Questions About Space Tourism
How does the current growth rate compare to past years? The industry has moved from an experimental historic period to a forecast period characterized by regularized service offerings and a steady CAGR of nearly 19%. This shift signifies that the market is no longer reliant on one-off missions but is supported by a consistent schedule of civilian flights.
What technologies are most vital for cost reduction? Reusable passenger launch systems remain the most critical technology, as they increase flight frequency while significantly reducing the price per seat for the average consumer.
Which region will dominate the next decade? While North America leads in volume, the Asia-Pacific region will likely see the highest growth rates due to massive regional tech investment and aggressive government support for commercial space initiatives. These developments suggest a future where the space tourism market is truly globalized, with multiple regional hubs across different continents competing for the same high-end clientele. As these regions continue to innovate and reduce launch costs, the accessibility of space will continue to improve, driving further market expansion and technological breakthroughs in the coming years.
Strategic Takeaways: The Path Toward Orbital Maturity
The assessment of the leisure space tourism sector demonstrated that the industry moved well beyond its experimental origins. The data indicated that a combination of reusable technology and robust private funding established a foundation for sustained multi-billion-dollar growth through 2030. It was observed that the convergence of military and civilian interests provided a unique tailwind for research, while regional competition served to accelerate the pace of innovation across the globe. The findings suggested that the focus shifted toward the development of private orbital habitats and more personalized luxury itineraries to maintain consumer interest.
As the market matured, it became clear that the most successful entities were those that prioritized safety and exclusivity in equal measure. Moving forward, the focus must remain on the expansion of orbital infrastructure and the enhancement of the passenger experience. The development of specialized habitats and personalized itineraries was identified as the next logical step in the industry’s evolution. Ultimately, the progress made during this period established a robust framework for a future where traveling beyond the atmosphere was a standard option for high-end adventure seekers, cementing its place in the luxury economy.