Petra Trust’s conservative yet growth-oriented investment strategy is designed to ensure that the fruits of a worker’s labor are preserved for several decades. This foundational principle has guided the firm since its establishment in 2011, but the current landscape of 2026 reveals a much more ambitious entity than a simple pension trustee. The company has successfully navigated the complexities of Ghana’s regulatory reforms to emerge as a total financial wellness partner. By moving beyond the mechanical collection of contributions, the organization now addresses the psychological and structural barriers that often prevent individuals from achieving true economic freedom. This evolution was not accidental; it was a deliberate response to a market where retirement was often viewed as a distant, abstract concept rather than a manageable goal. Today, the firm serves as a multidisciplinary hub where brokerage, investment advisory, and real estate solutions converge to offer a holistic approach to wealth management. This strategy transforms the traditional view of a pension provider from a passive custodian into an active life partner that supports workers from their first paycheck through to their legacy planning phase. The firm’s methodology emphasizes that financial independence is not a destination reached at age sixty but a continuous process of stability and growth.
Building a Foundation for Economic Stability
The Hierarchy: Mandatory and Optional Savings
The framework for financial wellness begins with a tiered hierarchy of needs, centered primarily on the mandatory and optional pension products that form the bedrock of a secure future. Tier 2 and Tier 3 offerings are not merely regulatory requirements but are positioned as essential safety nets that provide the foundational security required before an individual can pursue more aggressive wealth-building strategies. By framing these pensions as a starting point rather than a final goal, the firm helps clients establish a reliable base for their future financial health. This structural approach ensures that every worker, regardless of their current income level, has a disciplined mechanism for saving that is protected from the volatility of immediate consumption needs. The focus here is on consistency and the power of compound interest, which works silently over the years to build a substantial corpus. This initial layer of the financial pyramid is critical because it mitigates the risk of poverty in old age, a concern that remains prevalent in many emerging economies. By securing these primary tiers, individuals gain the psychological confidence necessary to explore more sophisticated investment opportunities that can further enhance their lifestyle and long-term security.
Stability First: Managing Emergency Liquidity
To protect long-term goals from being derailed by unforeseen circumstances, there is a significant emphasis on the importance of emergency and stability tools. The firm encourages the creation of liquid emergency funds that cover several months of income, utilizing specialized vehicles like the Fixed Income and Plus Income funds. These products are specifically designed to offer a balance of safety and liquidity, ensuring that clients do not have to liquidate their retirement savings prematurely when faced with urgent life challenges such as medical emergencies or sudden unemployment. Maintaining a clear distinction between long-term “patient capital” and short-term “emergency capital” is a hallmark of this wellness strategy. Without this buffer, even the most robust pension plan can be compromised by the immediate need for cash. These stability products allow for a “liquid-first” mentality that provides a sense of security, allowing the primary retirement assets to grow undisturbed. This dual-track approach—building for the future while shielding the present—creates a resilient financial profile for the individual. It addresses the reality that life is unpredictable and that a truly comprehensive financial plan must account for the unexpected without sacrificing the promise of a comfortable retirement several years down the line.
Advancing Toward Wealth Creation and Legacy
Growth Strategies: Hedging and Passive Income
Once a client achieves a baseline of stability, the focus shifts toward active wealth accumulation and the generation of passive income through more advanced channels. The firm facilitates this growth through sophisticated investment vehicles, including Eurobond Trusts and dollar-indexed options that help hedge against local currency fluctuations. These instruments are vital for maintaining purchasing power in an environment where inflation can erode the value of traditional savings. The ultimate objective is to move individuals toward a state of financial independence where their lifestyle is sustained by their assets rather than solely by their active labor. This transition requires a shift in mindset from simple saving to strategic investing, where capital is deployed across different asset classes to maximize returns while managing risk. By providing access to international markets and diversified portfolios, the firm empowers the average worker to build a level of wealth previously reserved for institutional investors. This democratization of high-level finance ensures that the path to prosperity is open to a broader segment of the population. As these passive income streams grow, they provide a secondary layer of security that complements the mandatory pension, offering a more robust and flexible financial future that can withstand various economic cycles.
Preserving Legacies: Real Estate and Life Insurance
The final stage of this holistic model involves the preservation and transfer of wealth to the next generation, ensuring that the fruits of a lifetime of work are not lost. Through a combination of life insurance offerings and strategic real estate investments, the firm provides a comprehensive roadmap that turns individual labor into generational security. Real estate, in particular, is viewed as a cornerstone of the Ghanaian dream, and by partnering with trusted developers, the organization offers affordable housing solutions that double as high-value assets. These tangible investments provide both a physical home and a store of value that can be passed down to heirs. Life insurance products further protect the family unit by providing a financial cushion in the event of the policyholder’s passing, preventing the sudden loss of income from destabilizing the household. This “cradle to grave” approach reinforces the firm’s commitment to the long-term prosperity of Ghanaian families, moving beyond the individual to consider the collective future of the lineage. By integrating these elements into a single cohesive strategy, the firm helps clients build a legacy that is both durable and meaningful. This focus on wealth transfer ensures that the economic progress made by one generation serves as a springboard for the next, fostering a cycle of growth and stability.
Modernizing Access Through Digital Innovation
Digital Reach: Bridging the Informal Sector Gap
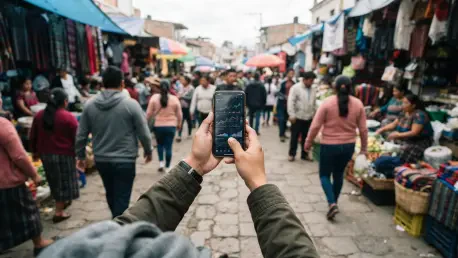
Central to the strategy for financial inclusion is a sophisticated mobile platform that has reached over 300,000 users, many of whom operate outside the traditional corporate environment. This tool bridges the gap between the formal and informal sectors by providing high-level financial literacy resources and real-time fund performance data directly to the user’s smartphone. By democratizing access to financial planning, the firm is fostering a culture of transparency and proactive management that was previously inaccessible to many citizens. The app serves as a generalized advisory tool that allows any user, regardless of their current pension status, to engage with wealth-building strategies and track their progress toward specific goals. This digital-first approach recognizes that in a mobile-centric economy, accessibility is the key to engagement. It removes the physical and bureaucratic barriers to entry, allowing market traders, artisans, and small business owners to participate in the formal financial system. The platform’s intuitive design makes complex financial concepts understandable, empowering users to take control of their economic destiny. By putting the power of a financial advisor in the pocket of every Ghanaian, the firm is laying the groundwork for a more inclusive and financially literate society where everyone has the tools to succeed.
Behavioral Finance: The Power of Pension Loans
Addressing the psychological barriers to saving is just as important as providing the financial tools themselves, and this is where innovative concepts like pension-backed loans come into play. Many younger workers feel disconnected from their retirement accounts because the benefits seem decades away, leading to a lack of engagement or a tendency to prioritize immediate spending. By allowing contributors to use their pension accounts as collateral for loans, the firm provides a tangible, immediate benefit to maintaining a healthy retirement balance. This feature enables clients to address pressing needs, such as home repairs or education costs, without breaking their investment cycle or losing the benefits of compound growth. It essentially turns the pension into a multipurpose financial asset that serves the client throughout their life, rather than just at the end of it. This strategy aligns the interests of the individual with their long-term savings goals, creating a positive feedback loop where the more they save, the more credit they can access. This behavioral intervention is a powerful tool for increasing retention and participation rates, as it demonstrates the practical utility of a pension in a way that resonates with the immediate concerns of the workforce. It transforms the perception of a pension from a locked-away fund into a dynamic resource for life management.
Investing in the Future of the Nation
Patient Capital: Funding National Progress
The investment philosophy is rooted in a conservative, growth-oriented approach that strictly follows national regulatory guidelines to protect the purchasing power of its contributors. However, beyond individual returns, the firm recognizes its role as a custodian of “patient capital” that can be channeled into national infrastructure and sustainable development projects. By investing in things like energy, transportation, and industrial growth, the organization ensures that while clients earn risk-adjusted returns, their capital is also being used to improve the economic environment in which they live and work. This dual-purpose strategy creates a symbiotic relationship between the individual’s savings and the country’s progress. When pension funds are used to build better roads or more reliable power grids, they contribute to a stronger economy, which in turn benefits the contributors through better job opportunities and a more stable currency. This macro-level impact is a critical component of the firm’s vision for financial wellness, as individual prosperity is inextricably linked to the health of the national economy. By acting as a bridge between private savings and public development, the organization plays a vital role in the sustainable growth of the nation, ensuring that the financial system serves the people in a holistic and impactful manner.
Future Horizon: Next Steps for Financial Wellness
The evolution of the financial sector over the past decade demonstrated that a narrow focus on simple savings was insufficient for the complex needs of the modern Ghanaian worker. Significant strides were made in integrating technology and behavioral science to create a more resilient population that viewed retirement not as an end, but as a phase of a well-planned life. To continue this momentum, individuals should now consider moving beyond mandatory contributions to explore diversified asset classes that offer protection against currency depreciation. For those in the informal sector, the immediate next step involved utilizing mobile platforms to establish automated micro-savings habits that mirrored the discipline of formal employment. The focus shifted toward creating a comprehensive “life portfolio” that included real estate and insurance as primary pillars rather than afterthoughts. As the industry looked forward, the integration of these services into a single, seamless experience became the standard, requiring clients to stay informed and proactive about their asset allocation. Looking ahead, the focus must remain on the long-term preservation of capital while leveraging new opportunities in the regional market to ensure that the growth achieved today remains sustainable for the generations to follow. By adopting these strategies, workers secured their future while contributing to a broader culture of economic excellence across the country.