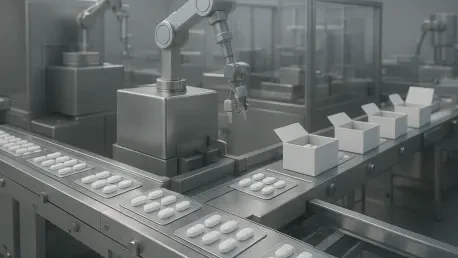
A single geopolitical event, such as a trade restriction or a closed shipping route, can now trigger a cascading effect throughout the entire medical supply chain. For several decades, the life sciences sector operated under a low-cost mandate that prioritized efficiency above all else. Supply chains were meticulously designed to maximize margins through global sourcing, often concentrating manufacturing and material procurement in regions where labor and overhead were most economical. However, this traditional framework is being dismantled by a new reality of stiff tariffs, fluctuating trade routes, and systemic disruptions. Companies are now being forced to move away from pure efficiency and toward a strategy centered on operational resilience to ensure the delivery of life-saving products. This transformation is not merely a reaction to current events but a fundamental restructuring of how pharmaceuticals and medical devices are brought to market. As the predictability of the early twenty-first century fades, the sector must confront the reality that lean operations are often fragile operations.
The End of the Low-Cost Mandate: Resource Scarcity and Trade
The era of the low-cost mandate in life sciences has officially ended, giving way to a landscape where the ability to withstand shocks is the primary objective for executives. Beyond the immediate impact of tariffs, which have become a standard tool of trade policy, the industry is grappling with a burgeoning crisis regarding access to rare earth elements. These materials are essential for high-tech diagnostic machinery and specialized laboratory equipment used across the value chain. Because the production of these elements is geographically concentrated, any geopolitical friction or trade restriction can immediately paralyze production capabilities. Consequently, firms must now prepare for a future defined by constant change and volatility rather than stable growth. This paradigm shift requires a complete re-evaluation of how manufacturing capacity is distributed globally. Manufacturers are increasingly moving away from long-established global hubs toward more secure, albeit more expensive, regional alternatives that offer protection from trade wars.
The drumbeat of tariffs serves as a primary catalyst for this shift, as financial barriers do more than just increase production costs; they fundamentally alter the risk profile of every organization. When trade policies cause sudden price spikes or limit market access, it forces insurers to reconsider their underwriting decisions and forces manufacturers to reconsider their entire production footprint. The reliance on offshore manufacturing for basic pharmaceutical ingredients has created a systemic vulnerability that is no longer acceptable to regulators or patients. To mitigate this, companies are investing in domestic or near-shore production facilities that can maintain operations even when international borders are tightened. This transition to resilience is costly and time-consuming, but it is necessary for long-term survival in an unpredictable economic climate. Building redundant systems and securing local sources of critical raw materials has become the new industry standard, replacing the old model of just-in-time delivery with a more robust just-in-case inventory strategy.
Modern Underwriting: The Challenge of Complexity and Speed
The methods used to evaluate risk in the life sciences industry have undergone a significant overhaul to match the modern reality of the global market. Experts identify complexity and speed as the two dominant forces currently reshaping how insurers assess potential clients and their vulnerabilities. In the past, underwriting was often a siloed process, looking at isolated factors like supplier concentration or contract manufacturing agreements. Today, these factors are deeply interconnected, meaning a single regulatory issue at a third-party sterilization plant can halt a company’s entire revenue stream overnight. Insurers are now diving deeper into these external relationships, examining the resilience of the entire partner ecosystem rather than just the primary company’s internal controls. This level of scrutiny is necessary because the majority of life sciences firms do not own the facilities where their products are manufactured or tested, creating a significant amount of contingent business interruption exposure.
A critical point of concern in modern underwriting is the velocity at which risks manifest in a digitally connected and geopolitically volatile world. When a shipping lane is blocked or a trade restriction is implemented, the impact is felt instantly across the entire supply chain, leaving little time for manual intervention. Underwriters are increasingly looking for companies that have implemented real-time monitoring and automated contingency plans to address these sudden shifts. The transparency of a company’s supply chain data has become a key factor in determining insurance premiums and coverage limits. Firms that can demonstrate a granular understanding of their dependencies are viewed as more favorable risks. This collaborative approach between the insured and the insurer ensures that the insurance program reflects the actual physical reality of the supply chain. By focusing on the speed of response and the complexity of the network, insurers help life sciences companies build a defensive posture that is capable of withstanding rapid environmental changes.
Physical Logistics: The Changing Geography of Global Trade
The physical movement of goods is becoming increasingly fraught with risk as geopolitical instability interrupts established shipping lanes and energy supplies. To bypass high-tariff markets or zones of conflict, companies are shifting trade routes toward non-traditional alternatives that may involve less mature infrastructure or different regional risks. This shifting geography of trade requires a constant re-evaluation of insurance coverage to ensure that goods are protected as they move through new territories. As the value of pharmaceutical products and medical devices flows through these evolving paths, the exposures change in real-time, making static insurance programs obsolete. To maintain adequate protection, companies and their insurers must engage in transparent discussions about the physical reality of their logistics. This ensures that the insurance program reflects where the products actually are rather than where they used to be, closing potential gaps in coverage that could be catastrophic during a logistical crisis.
Beyond the routes themselves, the stability of energy supplies and transport hubs has become a major variable in supply chain planning. Life sciences products often require strict temperature controls and specialized handling, making them highly sensitive to delays or power failures at transit points. As companies diversify their logistics providers to avoid over-reliance on a single hub, they must also ensure that these new partners meet rigorous quality and safety standards. This diversification adds another layer of management overhead but is essential for maintaining the integrity of the medical supply chain. The move toward more regionalized trade blocs is also changing the way products are distributed, with an emphasis on shorter, more direct routes that reduce the chance of international interference. By aligning logistics strategies with regional trade agreements, firms can minimize the impact of tariffs while ensuring a more reliable flow of goods to the patients who depend on them for their health.
The Dual Impact: Artificial Intelligence and Risk Profiles
Artificial Intelligence is acting as a double-edged sword within the life sciences risk equation, offering both unprecedented tools for resilience and new categories of liability. On the positive side, AI serves as a powerful tool for building resilience by allowing companies to stress-test various supply chain scenarios and identify vulnerabilities before they manifest as crises. By simulating disruptions such as labor strikes, natural disasters, or trade embargoes, firms can develop more robust contingency plans and optimize their response strategies. This proactive use of technology is becoming a cornerstone of modern risk management, enabling leadership to make data-driven decisions that protect the organization’s operational continuity. However, AI also introduces speed-based risks that can outpace human intervention if not properly managed. If an AI model is built on biased data or flawed logic, it can amplify errors at a scale and velocity that are difficult for traditional oversight mechanisms to intercept.
Furthermore, AI is expected to shift the labor market within the industry, changing the skills and job requirements necessary for success while creating long-term workforce risks. The automation of laboratory processes and data analysis reduces the chance of human error but introduces risks related to software malfunctions and cybersecurity vulnerabilities. Both companies and insurers must closely monitor these technological developments to ensure that the drive for innovation does not inadvertently create new, unmanageable liabilities. From an underwriting perspective, the use of AI in drug discovery and clinical trials changes the nature of professional liability and product risk. As algorithms take on more decision-making responsibility, the question of accountability becomes more complex. Firms that implement strong governance frameworks for their AI systems are better positioned to navigate these challenges. The goal is to leverage the predictive power of AI to anticipate risks while maintaining enough human oversight to prevent algorithmic failures from causing widespread systemic damage.
Strategic Mapping: Forging a Pathway to Future Resilience
To thrive in this new normal, life sciences companies adopted a proactive, data-driven approach to risk by mapping every critical node in their supply chain. This went beyond knowing the primary supplier; it required a granular understanding of the supplier’s suppliers and the geographic concentration of raw material sources. Identifying these deep-seated dependencies allowed companies to spot potential bottlenecks before they caused a total operational shutdown. It was found that a major obstacle to agility was the high level of regulation in the industry, which made switching to alternative partners a months-long process involving intensive quality audits and regulatory filings. Therefore, those who succeeded were the ones who pre-qualified alternative suppliers long before a crisis hit. They understood that in a highly regulated environment, a backup plan had to be as rigorously compliant as the primary plan to be effective. This preparation ensured that production could continue even during severe global market disruptions.
The transition to a resilience-centric model was confirmed as an inescapable necessity rather than a strategic choice. Successful firms embraced their insurance providers as strategic intelligence partners, utilizing bespoke research to filter global macroeconomic developments through a risk-management lens. This collaboration allowed for more accurate pricing and relevant advice, helping organizations gain a competitive edge in a volatile market. It was ultimately concluded that the ability to turn risk intelligence into operational resilience was the defining characteristic of industry leaders. They shifted from reactive postures to states of strategic readiness, ensuring the continuity of life-saving medical supplies. By investing in regional manufacturing, diversifying logistics, and implementing robust AI governance, these companies built the foundations for long-term stability. The future of life sciences now depends on maintaining this commitment to flexibility and transparency, ensuring that the global medical supply chain remains functional regardless of the geopolitical or economic pressures that may arise.