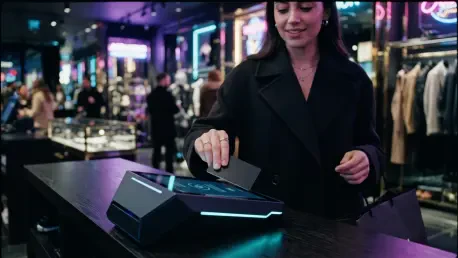
The loss of a stablecoin’s one-to-one peg with the dollar represents a unique systemic risk that necessitates robust risk management frameworks for any business holding digital assets. This reality remains the central focus for financial institutions and fintech innovators as the global market moves toward the full integration of blockchain-based settlement. The launch of the OKX stablecoin-denominated spending card on November 2, 2026, serves as a significant milestone in this journey, transforming digital tokens from speculative investment vehicles into functional instruments for daily commerce. While the card is marketed as a consumer product, its technical architecture provides a sophisticated case study for how decentralized finance interacts with the traditional merchant ecosystem. By allowing users to spend USDC, USDT, and USDG directly at any point-of-sale terminal, OKX is effectively narrowing the gap between digital asset wallets and the global payment rails that define modern retail and enterprise finance.
Market Infrastructure: The Evolution of Stablecoin Utility
Technical Foundations: Merging Blockchain with Legacy Payment Rails
The technical framework supporting the OKX spending card demonstrates a high level of sophistication in real-time currency conversion and liquidity management. Unlike early cryptocurrency debit cards that required manual pre-loading or suffered from significant price slippage during transactions, the 2026 model utilizes deep liquidity pools to facilitate instantaneous “just-in-time” conversions. When a transaction is initiated, the platform calculates the necessary stablecoin balance and executes a conversion to fiat currency that is entirely invisible to the merchant. This seamless integration ensures that businesses receiving payments do not need to alter their existing POS hardware or software, as the digital asset conversion occurs within the OKX settlement layer before the funds ever enter the traditional banking network. By absorbing interchange and conversion costs, the issuer is not only enhancing user experience but also setting a new benchmark for cost-efficiency in the fintech sector.
This shift toward fee-free digital transactions places immense pressure on traditional financial institutions to justify their existing fee structures. For decades, the global payment landscape was dominated by a handful of legacy players who charged substantial percentages for the privilege of moving value across their networks. The emergence of stablecoin-based cards signals a fundamental disruption of this model, as the underlying blockchain technology enables near-zero marginal costs for transaction processing. As these digital assets become more accessible, the value proposition for consumers and businesses alike shifts toward platforms that prioritize speed and transparency. The success of this launch suggests that the technical barriers that once hindered crypto adoption, such as high “gas fees” and slow confirmation times, have been largely mitigated by the advancement of layer-2 scaling solutions and high-throughput settlement protocols.
Scaling Financial Operations: The Rise of Wholesale Settlement
The infrastructure developed for retail stablecoin cards acts as a vital precursor to enterprise-grade digital finance tools. While a spending card typically handles relatively small consumer outflows, the underlying technology—comprising audited custody solutions and automated settlement layers—is increasingly being adapted for wholesale applications. For global enterprises, the ability to settle obligations instantly without the delays inherent in correspondent banking represents a significant competitive advantage. As seen in recent pilots by the HKMA and other central banks, the transition to tokenized settlement allows for “programmable money” where payments can be automatically triggered upon the fulfillment of specific contract conditions. This evolution from a consumer-focused card to a B2B treasury solution is the natural trajectory for the industry as it seeks to replace the slow and often opaque systems of the past.
The economic implications of this transition are substantial, particularly regarding the reduction of foreign exchange friction. Conventional cross-border payment systems often involve multiple intermediary banks, each extracting a fee and adding to the total settlement time, which can result in total costs reaching between three and five percent of the transaction value. In contrast, stablecoin networks facilitate direct peer-to-peer or platform-to-platform transfers that bypass these legacy hurdles entirely. As more businesses witness the efficiency of stablecoin cards in the retail sector, the demand for “wholesale” digital tokens is expected to grow, leading to the development of sophisticated corporate treasury dashboards. These systems allow for real-time visibility into global liquidity, enabling treasurers to move funds across borders in seconds rather than days, which fundamentally alters how organizations manage their working capital and mitigate currency volatility.
Regulatory Dynamics: A Fragmented Global Landscape
The American Regulatory Climate: Managing Uncertainty
Navigating the regulatory landscape in the United States remains a complex challenge for digital asset providers despite the rapid pace of technological innovation. Currently, the U.S. operates under a dual-track system where stablecoin issuers must manage a fragmented patchwork of state-level money transmitter licenses while simultaneously anticipating federal oversight. This regulatory environment creates a high barrier to entry and persistent legal uncertainty, as different states may have conflicting requirements for reserve transparency and consumer protection. While the GENIUS Act of 2025 was designed to establish a comprehensive federal floor for stablecoin regulation, its full implementation is not expected until at least 2027. Consequently, companies like OKX must adopt a highly agile compliance strategy, ensuring that their product offerings are tailored to meet the specific legal standards of each jurisdiction in which they operate.
This fragmented approach often places American firms at a disadvantage compared to their international counterparts who benefit from more unified regulatory structures. For a business seeking to integrate stablecoins into its operations, the lack of a clear federal mandate means that every transaction must be scrutinized through the lens of multiple legal frameworks. This necessitates the use of robust screening tools and automated compliance protocols that can verify the legal status of both the assets and the counterparties involved in real time. Despite these hurdles, the drive toward federal clarity is gaining momentum, with many industry leaders advocating for a system that provides the security of a federal charter while allowing for the innovation typical of the state-level system. Until such a framework is finalized, the burden of proof regarding solvency and asset backing remains on the individual issuers, who must prove their stability through frequent third-party audits and public disclosures.
International Standards: The MiCA Framework and Beyond
In contrast to the localized approach of the United States, the European Union has taken a decisive lead in providing regulatory clarity through the Markets in Crypto-Assets (MiCA) regulation. Since its activation in mid-2024, MiCA has provided a unified licensing regime that allows digital asset service providers to operate across all member states under a single set of rules. This framework sets rigorous standards for “e-money tokens,” including mandatory liquid reserves, clear redemption rights for consumers, and strict governance requirements for issuers. For global firms, the predictability of the E.U. market makes it an attractive destination for launching new stablecoin-based financial products. The transparency provided by MiCA not only protects consumers but also provides businesses with the legal certainty needed to invest in long-term digital asset strategies without the fear of sudden regulatory shifts.
The success of the E.U. model is influencing other major financial hubs, such as Singapore, Japan, and the United Kingdom, to adopt similar transparency-focused frameworks. These jurisdictions are increasingly prioritizing the safety of digital assets by requiring issuers to hold reserves in high-quality liquid assets like short-term government debt or cash equivalents. By standardizing these requirements, global regulators are fostering an environment where stablecoins can be integrated into the broader financial system with minimal risk to overall stability. This international convergence on regulatory standards is crucial for the continued growth of the digital finance sector, as it allows for the development of cross-border payment networks that are both efficient and secure. For a business operating globally, adhering to these emerging international standards is no longer just a legal requirement but a strategic necessity to ensure continued access to the world’s most advanced financial markets.
Strategic Implications: Corporate Treasury and Risk
Efficiency Gains: Optimizing Cross-Border Settlements
The strategic adoption of stablecoins within corporate treasuries offers a transformative opportunity to optimize global financial operations. For any organization with a multi-national footprint, the traditional process of managing liquid assets across different currencies is fraught with inefficiency and high overhead costs. By utilizing dollar-pegged stablecoins as a medium of exchange, companies can effectively centralize their liquidity management, reducing the need for multiple local currency accounts and the associated maintenance fees. This approach allows for the near-instantaneous movement of funds between subsidiaries, enabling a more dynamic response to market changes and funding requirements. Furthermore, the use of blockchain technology provides an immutable ledger for every transaction, simplifying the audit process and enhancing the overall transparency of the corporate financial structure.
Implementing these digital asset tools requires a thorough integration with existing accounting and reconciliation systems to ensure that every transaction is correctly recorded for tax and reporting purposes. The complexity of tracking “gas fees,” minor price discrepancies, and real-time exchange rates necessitates the use of advanced software that can bridge the gap between on-chain data and traditional enterprise resource planning tools. For firms that successfully navigate this integration, the rewards are significant, including the ability to offer faster payments to vendors and more flexible payroll options for a global workforce. This level of operational efficiency was previously unattainable under the legacy banking model, where the settlement of a single cross-border invoice could take several business days and involve numerous manual interventions. As the infrastructure matures, the transition to a digital-first treasury model is becoming an essential component of a modern corporate strategy.
Actionable Next Steps: Future-Proofing Digital Finance
The successful deployment of stablecoin payment solutions throughout 2026 provided a definitive blueprint for organizations seeking to capitalize on the next wave of financial innovation. Proactive treasury managers recognized that the separation of fiat and crypto rails was essential for maintaining a compliant and secure environment. By partnering with licensed financial institutions that offered segregated custody and real-time AML screening, these firms mitigated the risks associated with counterparty default and regulatory non-compliance. The implementation of multi-signature governance protocols further protected corporate assets, ensuring that no single individual could move significant funds without proper oversight and authorization. These measures proved vital as the industry transitioned from simple consumer spending toward more complex B2B applications, such as automated USDC-based payroll and instant vendor settlement.
Looking back at the progress made, it was clear that the most successful firms were those that treated digital assets not as a separate experiment, but as a core component of their broader financial ecosystem. They invested early in the necessary infrastructure and developed robust internal policies that prioritized reserve transparency and 1:1 redemption guarantees. As the regulatory environment in the United States began to stabilize with the anticipation of 2027 federal standards, these early adopters found themselves at a significant advantage, already possessing the tools and experience needed to navigate a fully regulated digital economy. The transition was characterized by a move away from speculative uncertainty toward a future defined by efficiency, transparency, and the seamless integration of global value. The lessons learned during this period established a new standard for how modern enterprises manage liquidity in an increasingly interconnected and digital world.