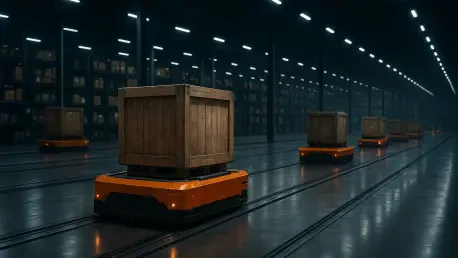
The shift toward industrial humanoids became evident when Holiday Robotics successfully closed a $106.9 million Series A round during the third quarter. This specific transaction serves as a bellwether for a much larger transformation currently reshaping the South Korean venture capital landscape throughout 2026. While the total volume of investments witnessed a sequential decline of 29 percent to reach $1.17 billion, the underlying stability in the number of deals—totaling 124 transactions—suggests a market that is consolidating rather than retreating. Investors are clearly moving away from the speculative fervor that previously defined the biohealth sector and are instead channeling their resources into tangible, industrial-grade technologies. This period of recalibration reflects a sophisticated understanding of global supply chain needs and a desire to leverage existing manufacturing prowess. The third quarter has redefined startup priorities, placing a premium on functional innovation over theoretical breakthroughs.
A Decisive Move: From Biohealth to Industrial Robotics
The most striking trend observed during the recent three-month cycle was the dramatic role reversal between the biohealth and robotics sectors. In the previous quarter, biohealth was the undisputed leader of the Korean startup economy, capturing over half of all disclosed funding through massive capital injections into drug development and genomic research. However, the third quarter witnessed a staggering 87 percent collapse in disclosed biohealth funding volume as large-scale rounds virtually vanished from the marketplace. Although the number of deals in health-related startups remained consistent with previous periods, the total capital was spread across much smaller, fragmented rounds. This shift suggests a cooling period for high-risk life science investments as venture capitalists seek more immediate returns on their capital. Meanwhile, robotics emerged as the new heavyweight, indicating that the era of speculative health tech may be giving way to the era of physical utility.
Robotics funding skyrocketed from a mere $68.6 million in the early months of the year to an impressive $403.7 million by the end of September. This surge was catalyzed by three primary transactions that highlighted the growing investor appetite for what industry experts are now calling Physical AI. Wonik Robotics secured a staggering $241.4 million, benefiting significantly from the strategic involvement of the National Growth Fund. Simultaneously, CarbonSix successfully raised $43 million in a Series A round specifically focused on implementing intelligent automation within complex manufacturing environments. These investments demonstrate a clear preference for technologies that bridge the gap between advanced software agents and heavy-duty physical labor. By focusing on industrial humanoids and autonomous logistics, South Korean startups are positioning themselves to address labor shortages and productivity bottlenecks in ways that software-only solutions simply cannot achieve.
The Influence: Policy Capital and Growth Equity
A recurring theme in the current investment landscape is the stabilizing influence of government-linked and policy-driven capital. The National Growth Fund, backed by the Korea Development Bank and the Financial Services Commission, has become the undisputed cornerstone of scale-up financing. In an environment where private liquidity can be volatile, these state-backed initiatives provide the necessary bedrock for massive funding rounds that allow national champions to compete on a global scale. The concentration of policy capital in the robotics and industrial technology sectors reveals a coordinated effort to modernize the nation’s manufacturing backbone. This symbiotic relationship between the public sector and private innovation ensures that even during periods of overall market contraction, strategically vital industries continue to receive the resources required for expansion. This structural support is essential for maintaining momentum in high-capital-intensity sectors like automation.
In addition to domestic policy support, global private equity firms are making increasingly visible inroads into the South Korean market. The second-largest deal of the third quarter involved Silicon2, which secured a $206.9 million investment from CVC Capital Partners. This single transaction was powerful enough to propel the commerce and consumer sector into the second-highest ranking for the quarter, highlighting the continued attractiveness of Korean consumer brands to international investors. These large-scale mega-deals, defined as rounds exceeding $20 million, collectively accounted for roughly 76 percent of the total disclosed funding for the period. The presence of international giants like CVC indicates that despite the 29 percent decline in total market volume, the top-tier opportunities in South Korea still command significant interest from global growth equity. This concentration of capital at the top suggests a flight to quality where only the most sound business models succeed.
Advanced Applications: Specialized AI and Content Media
Artificial intelligence continues to act as a magnet for venture capital, though the primary focus is narrowing toward specialized services and agentic AI. Three major companies closed significant Series C follow-on rounds during the third quarter, reinforcing their market positions against both domestic and international competition. Wrtn Technologies raised $69 million for its AI-driven entertainment platform, while Enhans secured $35.3 million to further develop its enterprise-grade agentic solutions. Liner also completed a $34.5 million raise to expand its sophisticated app-connection tools designed for autonomous AI agents. These substantial growth-stage rounds suggest that the AI sector is maturing beyond the hype cycle, with investors doubling down on companies that have demonstrated verifiable market fit and technological reliability. Instead of chasing general-purpose models, the current trend favors startups that can provide specific, actionable utility for businesses and consumers.
The content and media sector also experienced healthy activity, totaling $117.6 million in investment across the quarter. A notable highlight in this category was Bunkerkids, which operates an AI character-chat application that has seen rapid adoption among younger demographics. The company successfully raised $10.3 million in a Series A round supported by a diverse consortium of investors, including Kolon Investment and BSK Investment. This trend indicates that the software layer of the South Korean startup scene is becoming increasingly sophisticated, effectively integrating AI into daily entertainment and communication. While hardware and industrial robotics are taking the lead in terms of total dollar amounts, the continuous innovation in content delivery and digital interaction remains a vital component of the broader ecosystem. The success of these platforms demonstrates how AI can be leveraged to create new forms of social engagement, paving the way for a more vibrant digital future.
Market Nuances: Investment Stages and Seasonal Trends
When examining the market by investment stage, a clear divide exists between transaction volume and total capital value. The seed stage remained the most active in terms of the sheer number of deals, with 39 separate rounds recorded during the third quarter. However, these early-stage transactions accounted for a relatively small fraction of the total capital, totaling only $9 million and averaging roughly $230,000 per deal. In stark contrast, Series A and subsequent growth rounds were where the bulk of the financing was concentrated, with Series A alone bringing in over $287 million across 20 transactions. This disparity highlights a healthy but competitive pipeline where only a fraction of new entrepreneurs successfully bridge the gap to more substantial institutional funding. Investors are being more selective than ever, prioritizing startups that show a clear path to profitability and those that have established a solid technological moat in their respective industries.
The third quarter also demonstrated how cultural factors and seasonal cycles can influence financial momentum within the region. Monthly deal flow was remarkably consistent throughout July and August, with approximately 50 transactions reported in each month. However, September saw a sharp decline in activity, with only 23 deals being officially announced. This slowdown is directly attributable to the Chuseok holiday period, during which business operations, formal negotiations, and public announcements traditionally pause across South Korea. This seasonal ebb serves as a reminder that the timing of a fundraise is just as critical as the pitch itself for startups operating in this market. While the temporary dip in September may have skewed the quarterly totals downward, it does not necessarily reflect a loss of fundamental confidence. Instead, it highlights the rhythmic nature of the local economy where traditional holidays still dictate the tempo of modern venture capital activities.
Future Considerations: Evaluating the Undisclosed Segment
A significant portion of the South Korean venture market continues to operate within an opaque segment, where companies confirm funding rounds without disclosing specific financial figures. In the third quarter, 57 separate startups reached investment milestones that remained confidential in terms of total dollars. This undisclosed segment is heavily weighted toward early-stage ventures in the biohealth and materials sectors, including companies like Studio Kiko and SpectraIntel. The high frequency of hidden deals in these areas suggests that while the era of massive biohealth mega-deals has temporarily subsided, there is still intense foundational activity occurring at the pre-Series A and seed levels. This grassroots innovation often precedes the next wave of major industry shifts, indicating that the pipeline for future growth remains full. The diversity of these smaller, quieter rounds across various industries illustrates a resilient economy that is not solely reliant on headlines.
The investment landscape of the third quarter confirmed that South Korea’s startup ecosystem entered a more disciplined phase of growth. The strategic transition away from speculative biotechnology toward industrial robotics and enterprise AI reflected a broader demand for immediate technological utility. Policy capital functioned as a vital stabilizer, ensuring that high-potential sectors received the necessary resources to scale despite a contraction in total market volume. For stakeholders looking ahead, the priority remained the integration of physical automation into the nation’s existing industrial infrastructure to combat demographic and productivity challenges. Moving forward, startups were encouraged to focus on operational efficiency and tangible market applications rather than pursuing inflated valuations based on software potential alone. This period of consolidation ultimately prepared the market for a more sustainable future where innovation is measured by its impact on the real economy.